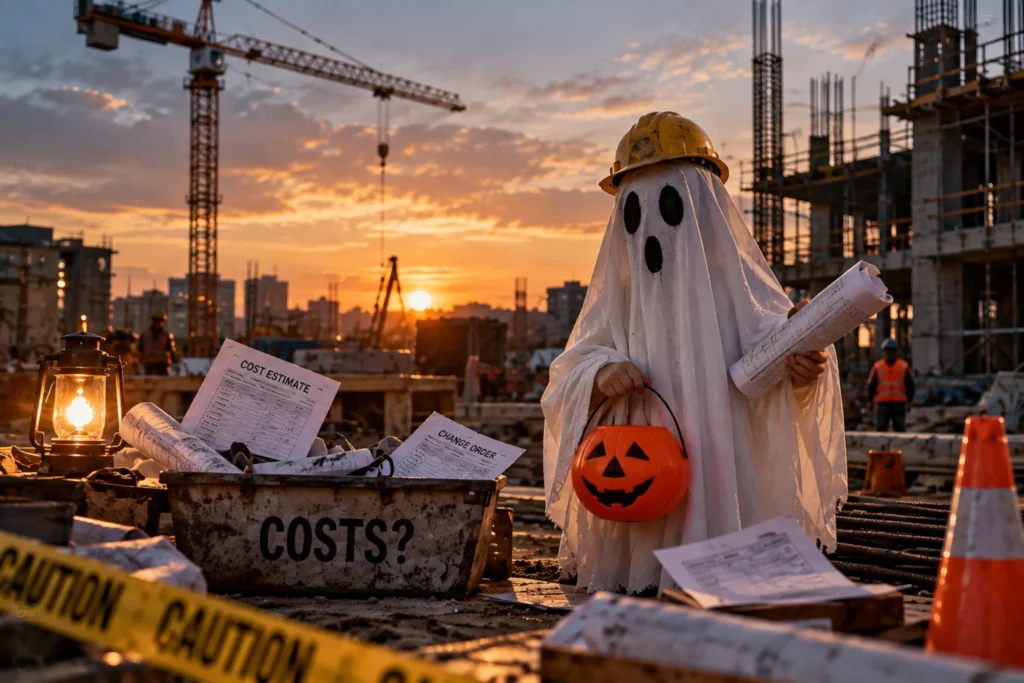
A “ghost budget” is an approved budget that no longer reflects the real status of the project.
This happens when the latest forecast leaves out changes, agreed purchases, risks, or required work missing from the original scope.
While the approved budget sets the spending baseline, the forecast estimates the total cost at completion. Keeping that estimate current helps owners see whether funding will cover the work ahead.
Industry figures also need context. They should be validated against actual project spend before they are declared in forecast estimates.
Take, for example, the Philippine Statistics Authority reported an average declared construction cost of ₱11,995.74 per square metre in July 2026, up 3.5% from July 2025. These preliminary figures come from approved building permits, not final project spending.
For owners reviewing project reports, the question is: what do these costs actually cover?
Budget gaps can begin before construction is underway.
As designs develop, some required work may remain unpriced. Teams need to check whether existing allowances cover it before relying on the reported budget balance.
For instance, a design review on an individual project may identify additional drains needed to manage rainwater on site. While the price is being agreed, the team should estimate the cost and check existing allowances. Any uncovered amount belongs in the forecast.
Track the additional work in a change register, a shared log of project changes. Note why the work is needed, its estimated cost, and how it could affect the schedule and the budget.
If approval is pending, identify who needs to decide and by when. This helps the team follow up before the work proceeds.
Build the forecast around five practical checks.
Include the cost of completed work even if invoices have not arrived. Payments can lag behind construction, so they will not show everything the project already owes.
Account for all remaining work and supplies. Include agreed contract and purchase order amounts, alongside estimates for work not yet contracted. Check against completed work to avoid counting costs twice.
Estimate the cost of pending changes after checking what the budget already covers. Update these estimates once prices are agreed.
Also, show how known risks are covered and how much contingency, the allowance for uncertainty, remains.
Supplier discussions before bidding can help clarify what the project needs. The Asian Development Bank’s (ADB) early market engagement guidance supports this approach.
Compare bids for the same required work and check what each includes. ADB’s April 2026 value-for-money framework also recommends considering the total cost of owning the asset, rather than purchase price alone.
Check whether revised schedules or unresolved risks affect the cost of finishing the work. Update the forecast to reflect those effects.
Regular reviews should then check that these updates are recorded and outstanding decisions are followed through.
Each revision should be traceable across project records.
Before each cost review, compare the change register with contract records, as well as the preliminary forecast estimate. Investigate differences to establish which figures need updating. Assign unresolved items to someone responsible for following them up.
If the revised forecast exceeds the approved budget, show the funding gap and options to address it. Identify the required decisions to move forward and set a date for approval.
Record the agreed action and update the forecast. At the next review, check whether the action was completed and how it affected the expected final cost.
A cost report should make the next decision clear.
Before reporting a budget balance elsewhere, confirm that the forecast covers the remaining work and unresolved changes. This helps owners decide whether funds are available or already needed to ship the project forward.
JCVA connects project delivery with cost consultancy.
Our Project Management and Construction Management services work alongside Quantity Surveying & Cost Consultancy. We support early cost planning and feasibility studies, followed by tender documentation and procurement strategy support.
During construction, our services include cost control and variation management, which address changes to contracted work. Contracts and claims advisory supports teams in handling related contractual issues.
Contact technical@jcvassociates.ph or visit https://www.jcvassociates.ph/.
We manage risks, build strong stakeholder relationships, and deliver solutions that reflect global best practices, backed by deep local industry knowledge.
If you're looking for a reliable partner to bring your vision to life, JCVA is here to build it with you.
 United States
 Australia
 United Kingdom